Texas Midterm Results: What They Mean for Your Commercial Property Loan

Terrydale Capital
Nov 9, 2026 8 Min read
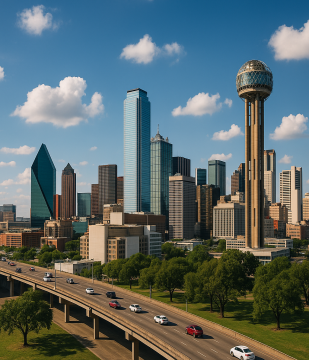
If you own commercial property in Dallas, Houston, Austin or San Antonio, you have probably been asked some version of the same question this week. Texas just elected a new governor and a new U.S. senator. Should you hold off on that refinance until you see what happens to property taxes?
For most borrowers, waiting on Austin costs more than it saves. The reasons come down to what a lender actually underwrites, and none of it depends on who won.
What changed on November 3
Democrat Gina Hinojosa defeated Governor Greg Abbott, and Democrat James Talarico won the U.S. Senate seat over Ken Paxton. Hinojosa is scheduled to take office in January. Republicans are projected to keep control of the Texas Senate, so any change to property tax law has to be negotiated with the Legislature rather than signed by a governor alone.
Nationally, Democrats won control of both chambers of Congress, and President Trump still holds the veto pen. Most analysts expect gridlock on taxes and spending.
The property tax proposals are not law
During the campaign, Hinojosa talked about paying for property tax relief by cutting corporate subsidies, ending sales tax exemptions for large data centers, and sending a one-time $1,500 refund to Texas households. All of it would need the Legislature to approve, and no specific timeline has been given. Her stated focus on property tax relief centers on homeowners and renters, so a commercial owner should not plan around a lower bill. Nothing here has been written into a bill yet.
Why your tax bill matters more than the election
Texas appraisal districts revalue commercial property every year, and the notice that lands in your mailbox in the spring matters far more to your lender than any campaign promise. Property tax is an operating expense. When we shop a loan, lenders size proceeds from net operating income and a minimum debt service coverage ratio, and the tax line sits right inside that calculation.
Take a hypothetical Dallas retail center with $600,000 of net operating income. A lender that requires a 1.25 DSCR will support $480,000 a year in debt service. Now say the next appraisal raises the tax bill by $45,000 and the leases do not pass it through. NOI falls to $555,000, supportable debt service falls to $444,000, and loan proceeds shrink by about 7.5 percent. On a loan that would otherwise have sized at $6 million, that is roughly $450,000 less.
That number moves because of your appraisal, your lease structure and your expense line, and it moves the same way under any governor. Triple-net leases soften the hit because tenants reimburse the increase. Gross and modified gross leases do not.
Rates are still set elsewhere
The other number in your loan is the rate, and neither the Legislature nor the governor sets it. Cushman & Wakefield said the election does not fundamentally alter its commercial real estate outlook. Its data shows private commercial real estate returns averaged 8.8 percent under unified government and 8.6 percent under divided government across 47 comparable periods. A gap of 0.2 percentage points is not a reason to delay a maturing loan. Treasury yields, spreads and lender appetite drive your pricing, and you can track the benchmark on our commercial index rate page.
Data center owners should read the fine print
Borrowers with data center projects should watch one proposal closely. Hinojosa said she wants to end sales tax exemptions for large data centers. If your build assumes that exemption, ask your tax advisor to model the project with and without it before you lock in a loan sized to the old numbers. Lenders will ask the same question, and it is better to have the answer before you submit. More on how these deals get structured is on our data center financing page.
When waiting makes sense
We start every one of these conversations with the maturity date, not the headlines. If your loan matures within the next 12 to 18 months, the bigger risks are a rate move or an appraisal notice that cuts proceeds, and either can land before the Legislature convenes in January. If you have two years or more of runway and a fixed rate you like, there is a reasonable case for watching what Austin actually passes.
Either way, we can shop your deal across our lender network and show you where the market sits today, so the decision to wait or move is made with a quote in hand rather than a guess. You can run a first pass on our refinance calculator, or request an advisory consultation if your maturity date is closer than you would like.
Partner With Terrydale Capital for Your Debt Financing Needs
When it comes to debt financing, understanding the right timing, process, and options is crucial. At Terrydale Capital, we provide a comprehensive range of commercial loan solutions tailored to meet your business's unique needs.







Success!
Product has been created successfully!
Headquartered in Dallas, Texas, Terrydale Capital is a leader in commercial real estate financing. We have close relationships with the nation’s top banks, lenders & family offices allowing us to provide the most competitive financing solutions in the market.


